How it works
One application. Every lender. One dashboard.
Your customer applies once. A full stack of lenders reviews that application in order, from the strongest programs to the broadest access. Your team manages every job in one place. Here is how each piece works, and what it does for your close rate.
01 · The customer experience
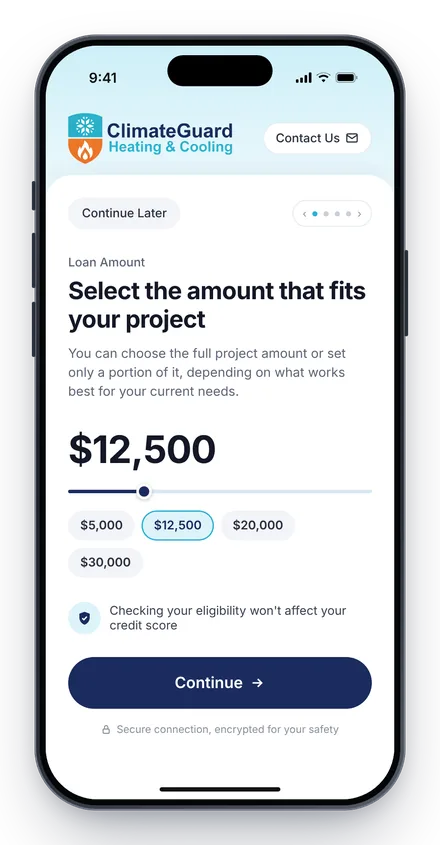
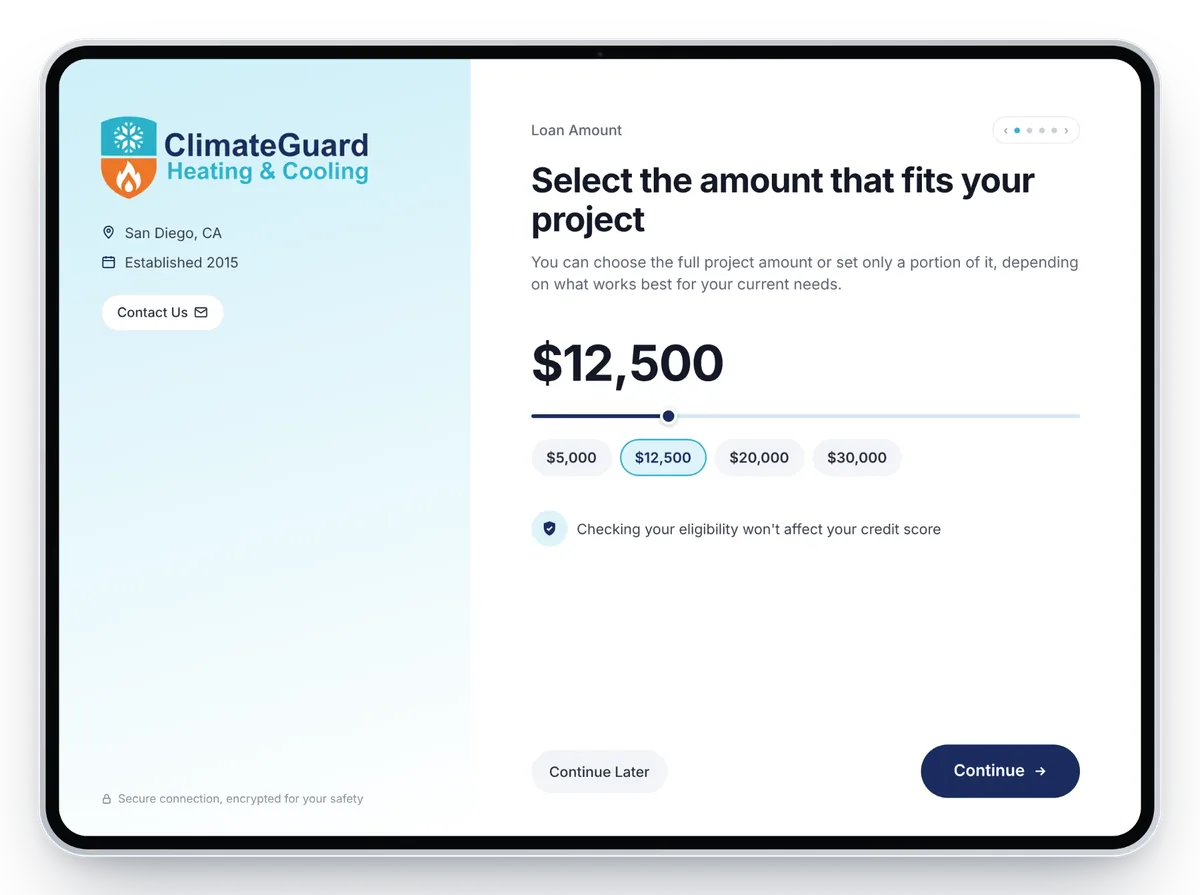
One clean application, wherever the conversation happens.
Your customer applies once, on their own phone or your rep's iPad. Checking eligibility uses a soft credit pull, so it won't affect their credit score. Offers come back side by side: lowest APR, lowest monthly payment and fastest payoff.
Send it any way your team works
- Rep's iPad
- QR code
- Text
- Web link
02 · The waterfall
Every lender has a credit box. The waterfall keeps going past it.
To see why a multi-lender stack wins more jobs, start with how a single lender decides.
What is a credit box?
Every lender approves a defined range of credit profiles. That range is its credit box. Inside the box, your customer gets offers. Outside it, they get a no, even when another lender would have said yes.
With one lender, that no ends the conversation. Your customer says "let me think about it," and the job quietly disappears.
U.S. consumers by FICO score tier
of U.S. consumers score below 670. If your lender's box starts above that line, so does your close rate.
Source: Experian, FICO Score 8 distribution, June 2026 data. Box position is illustrative.
The waterfall: where one lender stops, the next one starts.
One application moves through a stack of lenders in order, from the strongest programs at the top to the broadest access at the bottom. If one box doesn't fit, the application keeps moving. Your customer never reapplies, and your rep never starts over.
Illustrative. Programs and lender counts vary by trade, state and lender, and each lender makes its own credit decision. Small-ticket programs also cover quick repairs in HVAC and plumbing.
03 · The team experience
One dashboard for every job, rep and dollar.
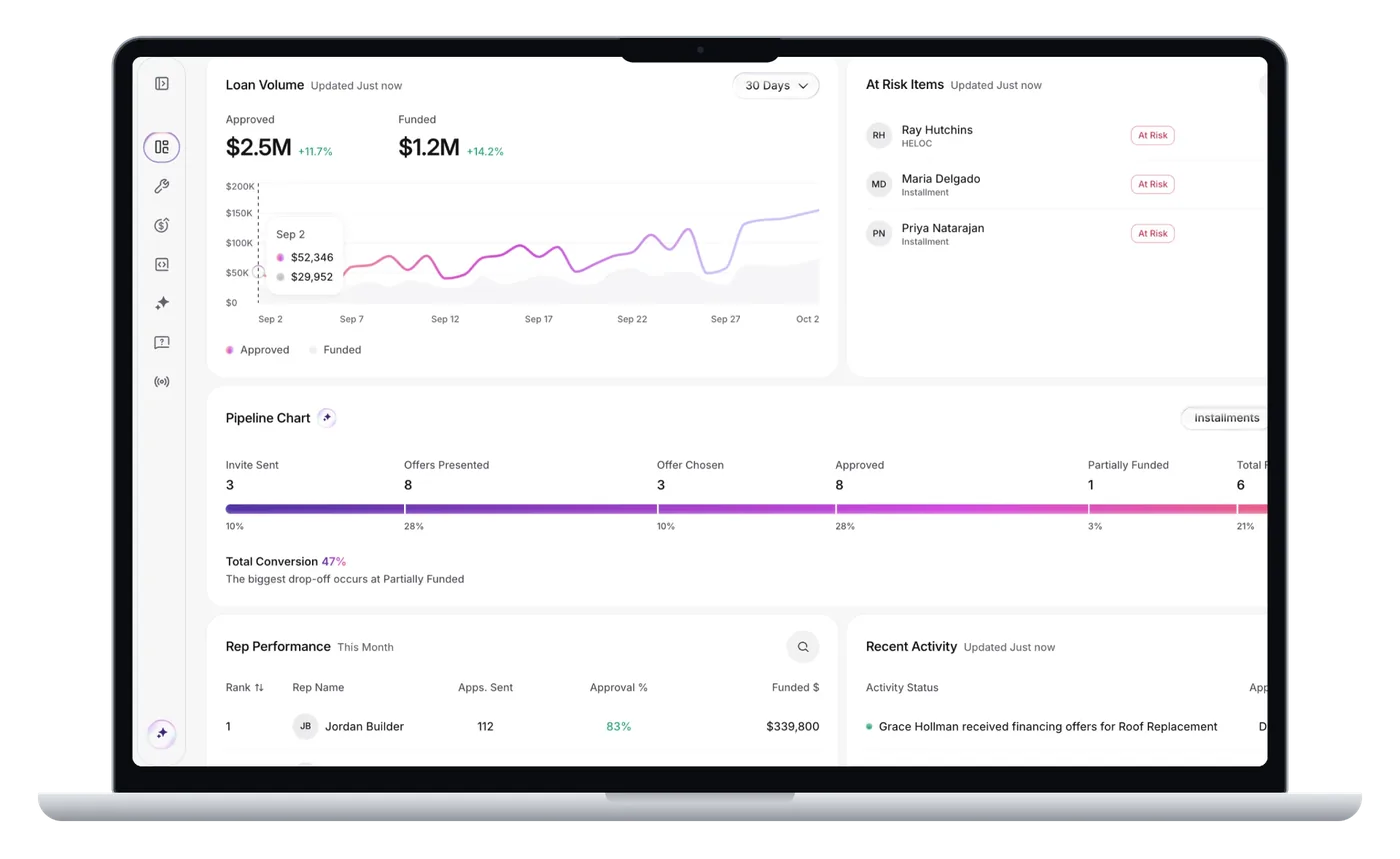
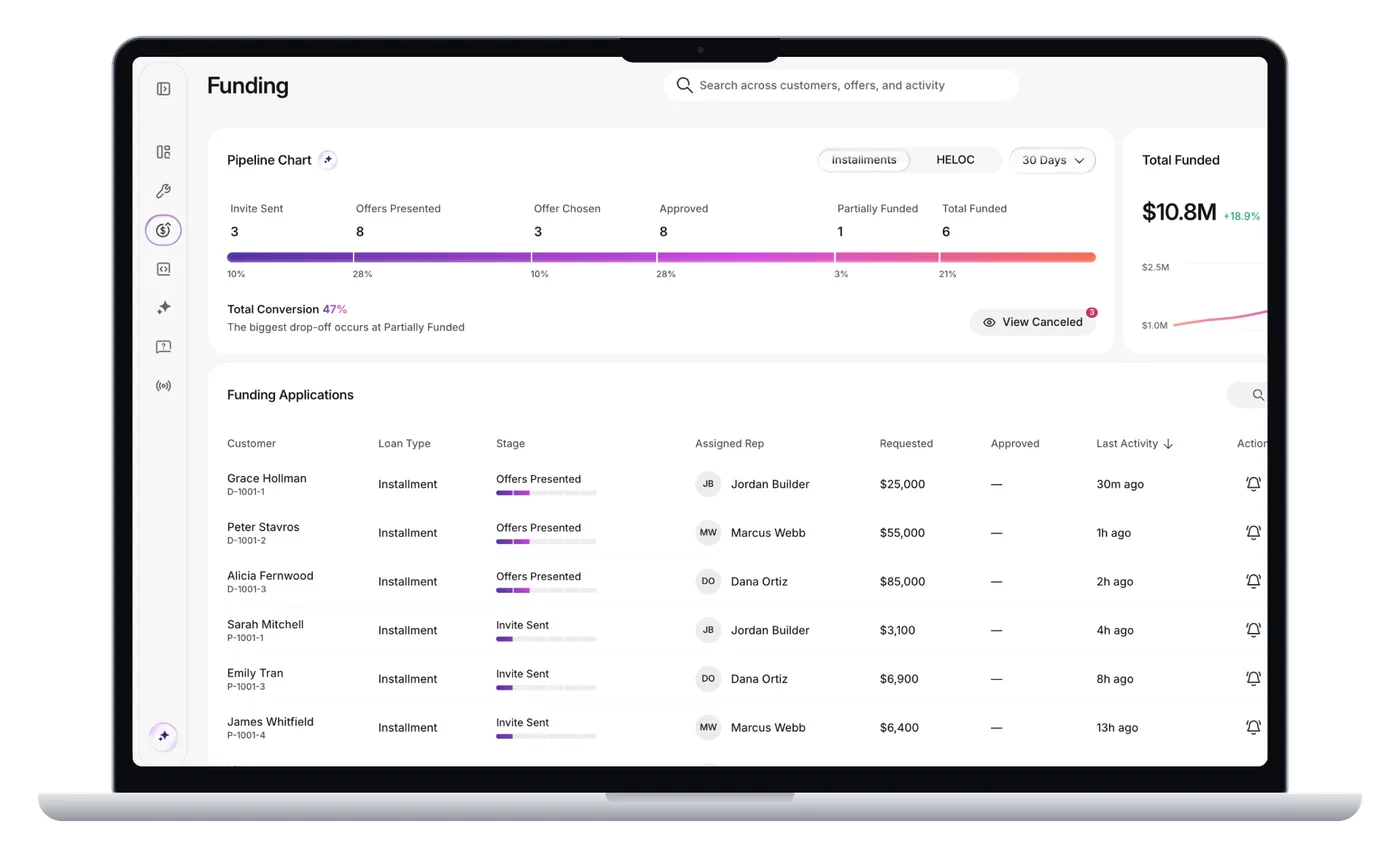
Every application, offer and funding status lives in one place. No portal, login or ledger per lender. Your managers see where deals stall while there is still time to save them.
Reporting and insight
Approved and funded volume, conversion at every stage and the step where deals drop off.
Application visibility
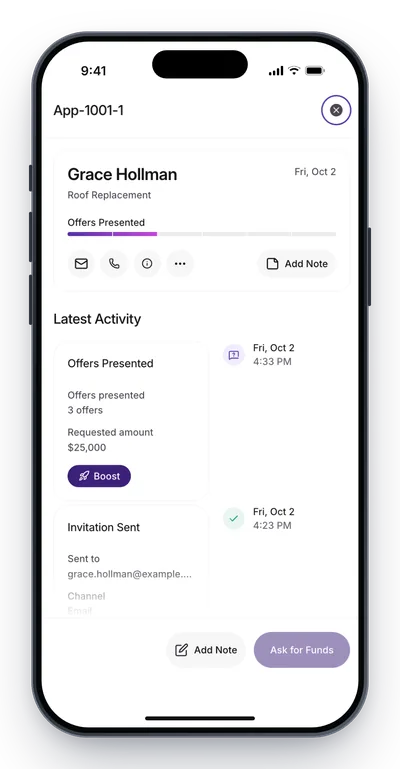
Every job by stage, with at-risk flags and the time left to act. Follow up, nudge or ask for funds from one card.
Custom branding
Your logo and colors on the customer application, so the experience stays yours from first tap to funding.
Team management
Add reps, assign jobs and compare performance: applications sent, approval rate and funded dollars by rep.
Built for the sales floor
Boost an approval. Close the job.
When a customer is approved, your team can boost the offer to a longer term the customer already qualified for, and turn a hesitant yes into a lower monthly payment.
04 · Getting started
From first call to first application.
Four steps, about an hour of your team's time. Lender approval of your business is the one step on the lenders' clock, and we keep you posted until it clears.
- Step 1Strategy call15 minutes
We look at your trades, your current lender lineup and where declines are costing you jobs.
Book a 15-Minute Call - Step 2Merchant applicationAbout 15 minutesApproval: varies by lender
Upload your business documents once. Each lender reviews on its own timeline, and we track every approval for you.
- Step 3Training and onboarding30 minutes
Your reps learn to send applications, present offers side by side and work the dashboard.
- Step 4ActivationFirst application
Send your first application. We review early results with you and tune your setup.
Get Started Now
Win More. Keep More.
One application. A full stack of lenders. One dashboard. No annual platform fee and no access fee, ever.
Transaction-level rates and fees vary by product and are disclosed at the time of application.