HVAC
How to Offer Financing to HVAC Customers: A 7-Step Setup
By Trevor Hansen· October 1, 2026· 5 min read
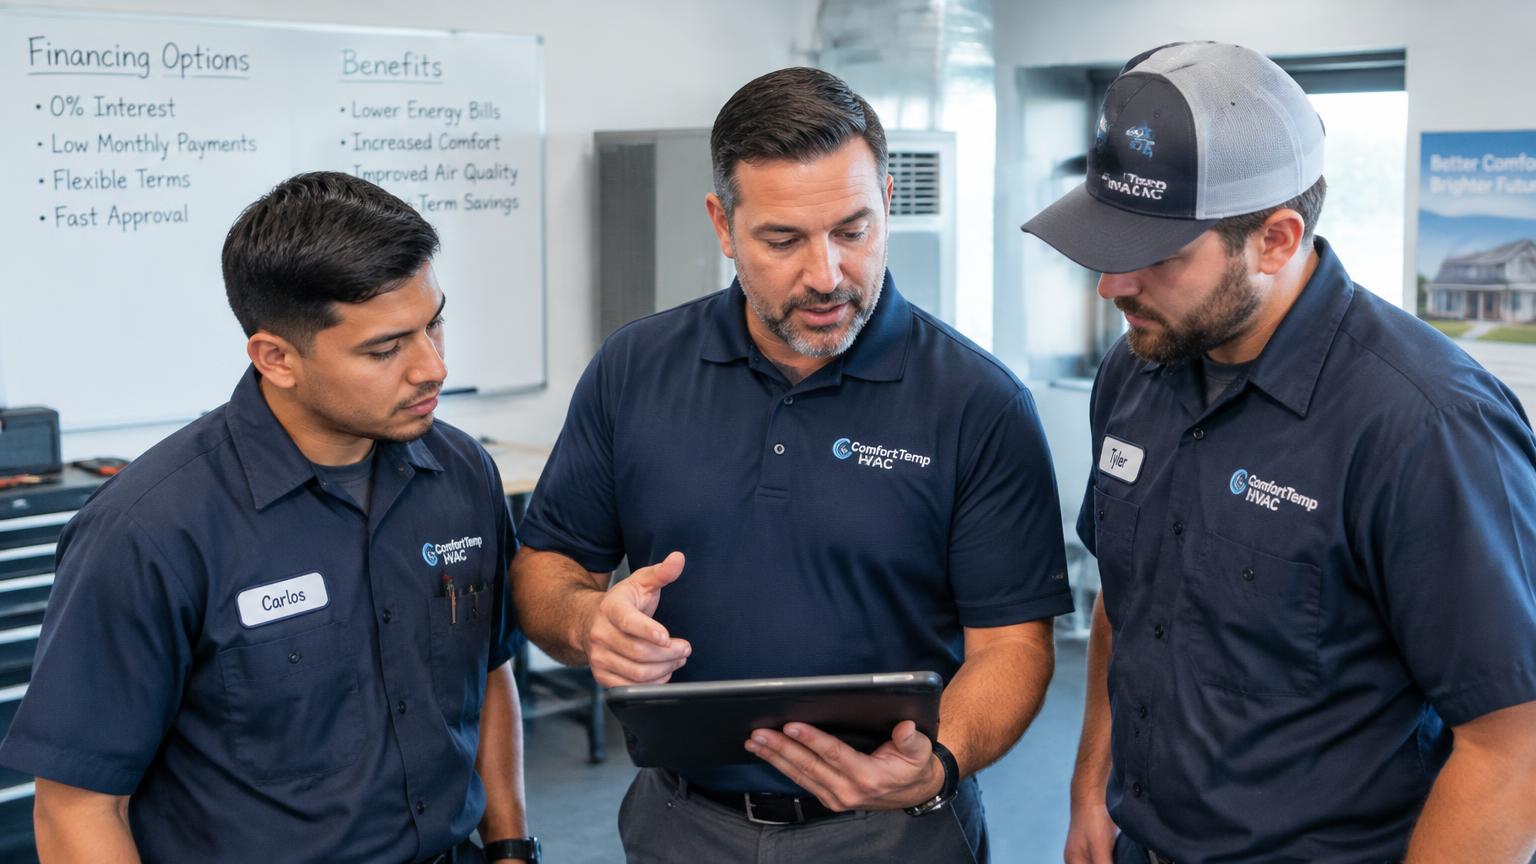
Most HVAC contractors who "offer financing" have a lender link buried in an email template. That is not a program. If you want to offer financing to HVAC customers in a way that closes jobs, it takes a short setup. Here are the seven steps, in order. For the bigger picture first, start with our HVAC financing overview.
Why how you offer financing to HVAC customers matters
Customers expect financing now. In the 2026 ACCA Contractor of the Future survey, contractors who offered financing reported a 49% close rate, against 38% for those who did not. Yet 32% of contractors surveyed still did not offer it at all.
The same survey shows the gap between offering financing and offering it well. Contractors who offered it on every job financed 18% more of their new and replacement sales than those who offered it case by case. The lender was the same. The habit was different.
Step 1: Decide what problem financing solves for you
Write down the one outcome you want. Most HVAC contractors pick one of three:
- Close more replacement jobs that stall on price.
- Raise the average ticket by making the better system affordable.
- Save declined customers who applied and walked.
Your answer decides which programs you need. A contractor chasing ticket size needs strong 0% APR options. A contractor losing declined customers needs coverage across credit tiers. Most contractors need all three, but knowing which one hurts most tells you where to start and what to measure first.
Step 2: Choose programs that cover your whole customer base
Map your customers to credit tiers, then make sure each tier has a program.
| Customer | What they want | Program that fits |
|---|---|---|
| Strong credit, has cash | Keep their savings | True 0% APR promotional |
| Strong credit, tight budget | Lowest monthly payment | Standard installment, longer term |
| Fair or thin credit | A yes | Extended credit spectrum lenders |
| Cannot get traditional credit | A working system | Lease-to-own, where available |
A single lender usually covers one or two rows well. That is why the decline rate is the number to watch.
Step 3: Put it behind one application
Every extra form is a chance for the customer to stop. Your customer should apply once and see what they qualify for. A multi-lender waterfall sends that one application to the next lender when the first says no, so a decline is not the end of the conversation.
Credit is not loose. The New York Fed's Credit Access Survey put the rejection rate for credit applicants at 16.1% in June 2026. In the same data, applications hit their highest level since late 2021. More people are applying, and a real share of them hear no.
16.1%
of U.S. credit applicants were rejected (June 2026)
Step 4: Price financing into your proposals
Financing has a cost, usually highest on promotional programs. Decide how you will handle it before your techs present it:
- Get each program's merchant cost in writing.
- Decide which programs you will offer on which job types.
- Build the expected cost into your pricing, the same way you build in commission.
Never add a surcharge at the table. It kills trust at the worst moment. Our post on HVAC financing dealer fees walks through the math.
Step 5: Put a monthly option on every proposal
Every proposal should show the total and at least one monthly option, in writing. The ACCA data backs this up. Contractors who led their proposals with a monthly payment saw a 21% higher share of financed sales.
Good, better, best proposals work well here. Show each tier with its total and its monthly option. The customer compares three monthly numbers instead of three large totals.
What a proposal line should look like. Keep it short and consistent across every tier:
Better system: total installed price, or a monthly option with a promotional or standard program. Program type named. Subject to credit approval.
The customer sees the same structure on every tier, so the comparison is about the system, not the math. Your office sees the same structure on every job, so reporting is simple.
Step 6: Train techs to present it without flinching
Most financing fails in the first 20 seconds of the conversation. The tech sounds apologetic, or asks "will you be paying cash?" and gets a yes.
Train three habits:
- Present options, not credit. "Most families here choose one of these monthly options" beats "do you need financing?"
- Stay with the customer while they apply. Walking away signals doubt.
- Know the next step if the first answer is no.
We wrote a full script in how to present HVAC financing.
Step 7: Track the numbers that matter
Review four numbers every month, by tech:
- Share of proposals where financing was offered.
- Share of customers who applied.
- Decline rate.
- Close rate on financed proposals.
The decline rate matters most. If 30% of your applicants get declined and half of them would have closed, you know what that gap costs. Use the What You're Missing calculator to put a dollar figure on it.
Five mistakes HVAC contractors make when they add financing
These show up again and again when contractors add financing without a plan.
- Offering it only when the customer balks. By then the customer has already decided the job is too expensive. Financing sounds like a rescue, not an option.
- Sending a link after the visit. The customer applies alone at night, gets a question they cannot answer, and closes the tab. The job goes to whoever was still in the kitchen.
- One lender, one answer. A single decline ends the conversation. Most contractors never learn how many jobs they lost this way, because nobody tracks it.
- Leading with deferred interest without explaining it. "Same as cash" programs charge retroactive interest if the balance is not paid in time. A customer who gets surprised by that bill remembers who sold it to them.
- Letting each tech invent the pitch. Your best closer and your newest tech should say roughly the same thing. A one-page script fixes this in a week.
Each of these is fixed by the steps above. The pattern is the same: financing works when it is planned, offered to everyone, and backed by more than one lender.
What a working setup looks like after 90 days
Once the setup is in place, a few things change. Techs stop treating financing as a last resort. Proposals carry a monthly option by default. Declines get a second look instead of a goodbye.
ServiceTitan's data shows financed HVAC jobs carry a median ticket 66% higher than comparable jobs customers chose not to finance. That is the prize. The seven steps above are how you get there. For the full picture of programs and providers, read our HVAC financing for contractors guide.
Frequently asked questions
How long does it take to start offering financing to HVAC customers?
Enrollment with a provider usually takes days, not weeks. The longer part is pricing your proposals and training your techs to present it, which is worth doing before the first customer sees it.
Should techs or office staff present financing?
The person presenting the proposal should present the financing. Splitting them sends the customer back to 'let me think about it.'
Do I have to offer financing to every customer?
You should offer it on every proposal. Deciding who 'needs' financing is how contractors miss the customers with good credit who would use it to protect their cash.
Sources
- ACHR News, From Perk to Expectation (ACCA survey) (2026-03-03)
- ServiceTitan, Financing in the Trades (2026)
- New York Fed, SCE Credit Access Survey (2026-07-20)