HVAC
HVAC Financing for Contractors: The 2026 Guide
By Trevor Hansen· October 2, 2026· 5 min read
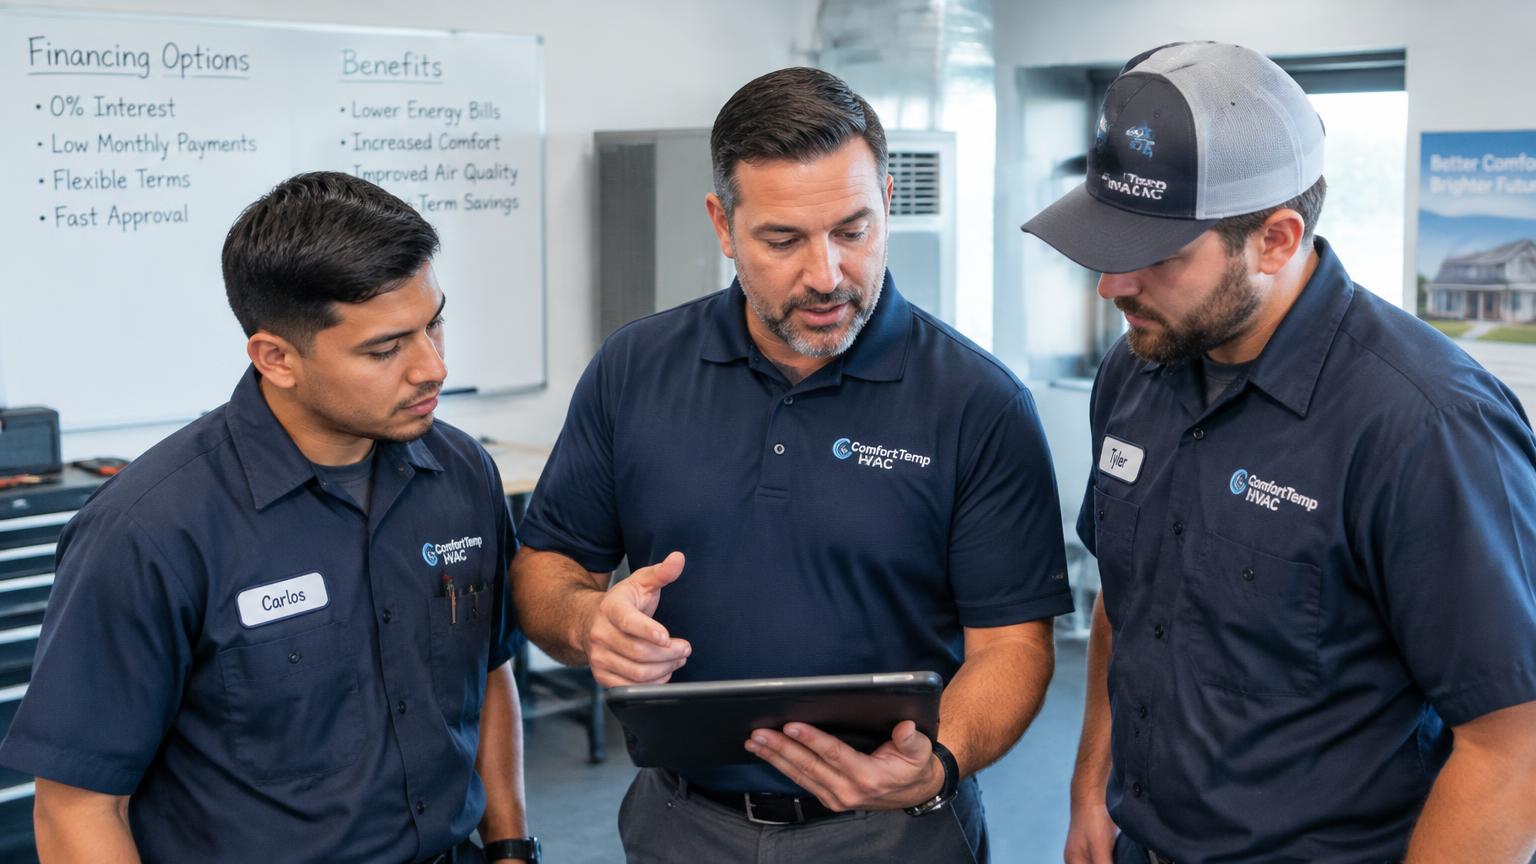
Customer financing used to be something HVAC contractors pulled out when a deal stalled. In 2026 it is part of how the job gets sold. This guide covers what the current data says, the program types you should know, and how to set up HVAC financing that closes more jobs without eating your margin.
Why HVAC financing matters more in 2026
Equipment got more expensive, and customers got more careful with cash.
The A2L refrigerant transition pushed equipment prices up in 2025, and tariffs added more on top. AHRI shipment data shows central AC and heat pump shipments fell 20% in 2025, to about 7.7 million units. Fewer units and higher tickets mean every proposal counts more.
On the customer side, the Federal Reserve's 2025 SHED report found only 63% of adults would cover a $400 emergency expense with cash. A failed condenser in July is a much bigger emergency than $400.
63%
of U.S. adults could cover a $400 emergency expense with cash or its equivalent
What financing does to close rate and ticket size
Two data sets from the last year point the same way.
- Ticket size. ServiceTitan's analysis of H2 2025 jobs found financed HVAC jobs had a median ticket 66% higher than comparable jobs the customer chose not to finance. ServiceTitan notes the finding is correlational, not causal.
- Close rate. In the ACCA Contractor of the Future survey of more than 1,000 contractors, close rates were 49% when financing was offered and 38% when it was not.
That is 11 more closed jobs out of every 100 proposals. On a replacement ticket, that adds up fast.
49% vs 38%
close rate for contractors offering financing vs not offering it
The ticket lift makes sense once you watch it happen. A customer who is paying cash picks the cheapest system that stops the problem. A customer comparing monthly options will often step up to the higher-efficiency unit, the better warranty, or the air quality add-on. The difference is a few dollars a month, not a few thousand today.
Offering financing on every job beats offering it sometimes
The same ACCA survey split contractors three ways: 37% offer financing on every job, 31% offer it case by case, and 32% do not offer it at all.
Contractors who offered it on every job saw 18% more of their new and replacement sales financed. The reason is simple. When a tech decides who "looks like" a financing customer, they guess wrong. Customers with good credit use financing to protect cash, and they never get asked.
The survey found a second habit worth copying. The 28% of contractors who lead proposals with a monthly payment, instead of the total price, saw a 21% higher share of financed sales. The total still goes on the proposal. It just is not the first number the customer sees.
What HVAC financing costs the contractor
Financing is not free, and a provider who says it is should make you nervous.
Promotional programs cost the most. When a customer gets 0% APR, someone pays for that money, and it is usually the contractor through a merchant fee. Standard installment programs usually cost the contractor less, because the customer pays the interest. Lease-to-own is priced differently again.
The right question is not "what is the fee?" It is "what does the fee buy me?" If a promotional program closes a job you would have lost, the fee is a cost of sale, like a commission. If it goes to a customer who would have paid cash anyway, it is margin you gave away. We break this down in HVAC financing dealer fees.
Two rules keep fees under control:
- Get every program's cost in writing before your team presents it.
- Price your proposals knowing which programs you will offer, so the fee is built in and never a surprise.
The program types HVAC contractors should know
You do not need every program. You need the right mix for your customer base.
| Program type | Best for | Watch out for |
|---|---|---|
| True 0% APR promotional | Prime customers who want to protect cash | Usually the highest merchant fee |
| Deferred interest ("same as cash") | Customers who will pay it off in the promo window | Retroactive interest if they do not |
| Standard installment | Customers who want the lowest monthly payment | Longer terms mean more total interest |
| Extended credit spectrum | Fair and thin-file credit | Pricing varies more by applicant |
| Lease-to-own | Customers who cannot get traditional credit | Not available in every state |
For a deeper look at the first two, read true 0% APR vs deferred interest.
Where most HVAC financing programs leak revenue
The biggest leak is the decline.
A customer loves the system, applies, and gets declined by your one lender. Now the tech is back to cash price, and the customer is back to "let me think about it." The job is usually gone.
Credit is tighter than it was. The Federal Reserve's July 2026 loan officer survey found a modest net share of banks tightened credit card standards again. A single-lender program feels that directly.
A multi-lender waterfall runs the same application through more than one lender, so more of your customers get an answer they can use. We cover this in detail in HVAC financing for customers with bad credit.
What changed for HVAC buyers in 2026
Two shifts make financing more important this year than last.
First, equipment costs more. Analysts at William Blair estimated the A2L refrigerant transition added 8% to 10% to equipment prices in 2025, with tariffs adding 2% to 3% more, as reported by Facilities Dive.
Second, a federal incentive went away. The Section 25C credit was worth up to $2,000 for a qualifying heat pump. It ended for systems placed in service after December 31, 2025, according to Honkamp's summary of the One Big Beautiful Bill Act. Customers who counted on that credit now need another way to close the gap. A monthly option is often that way.
How to set up an HVAC financing program that works
- Pick coverage over a logo. Choose a provider that covers prime through subprime, plus a lease-to-own option for HVAC.
- Make it one application. Your customer should apply once, not once per lender.
- Match funding to your install. Most HVAC replacements finish in a day. Your financing should fund like it, without construction-style draws.
- Train the presentation. Lead with options, not with credit. See how to present HVAC financing.
- Offer it on every proposal. Put a monthly option on every quote, in writing.
- Track declines. Know your decline rate by tech and by month. You cannot fix what you do not count.
How to choose between HVAC financing providers
Ask every provider the same five questions:
- How many lenders see my customer's application?
- Do you offer true 0% APR, or only deferred interest?
- What does each program cost me, in writing?
- How fast do I get funded after a same-day install?
- Can my whole team see every application in one place?
We compare the main options in best HVAC financing programs.
Frequently asked questions
Do HVAC contractors need a license to offer customer financing?
In most cases the lender holds the lending license and the contractor acts as the point of sale. Rules vary by state, so confirm with your provider and your own counsel before you advertise financing.
Does offering financing cost the contractor money?
Often, yes. Promotional programs such as 0% APR usually carry a merchant fee because the contractor is buying down the customer's rate. Standard installment programs usually cost the merchant less. Fees vary by lender and program.
How many HVAC contractors offer financing?
In the 2026 ACCA survey, 37% offered financing on every job, 31% offered it case by case, and 32% did not offer it at all.
What should I look for in an HVAC financing provider?
Coverage across credit tiers, true 0% APR options, fast funding on same-day installs, one application for the customer, and one dashboard for your team.
Sources
- ServiceTitan, Financing in the Trades (2026)
- ACHR News, From Perk to Expectation (ACCA survey) (2026-03-03)
- Contracting Business, AHRI 2025 year-end shipments (2026)
- Federal Reserve, SHED 2025 (2026-05-13)
- Federal Reserve, Senior Loan Officer Opinion Survey, July 2026 (2026-08-03)
- Facilities Dive, A2L transition and tariffs not yet slowing HVAC sales (2025)
- Honkamp, Impact of the One Big Beautiful Bill Act on residential energy credits (2025)